
Closing Tickets, Losing Loyalty: Why Banks Still Get Conversational AI Wrong
Closing Tickets, Losing Loyalty: Why Banks Still Get Conversational AI Wrong
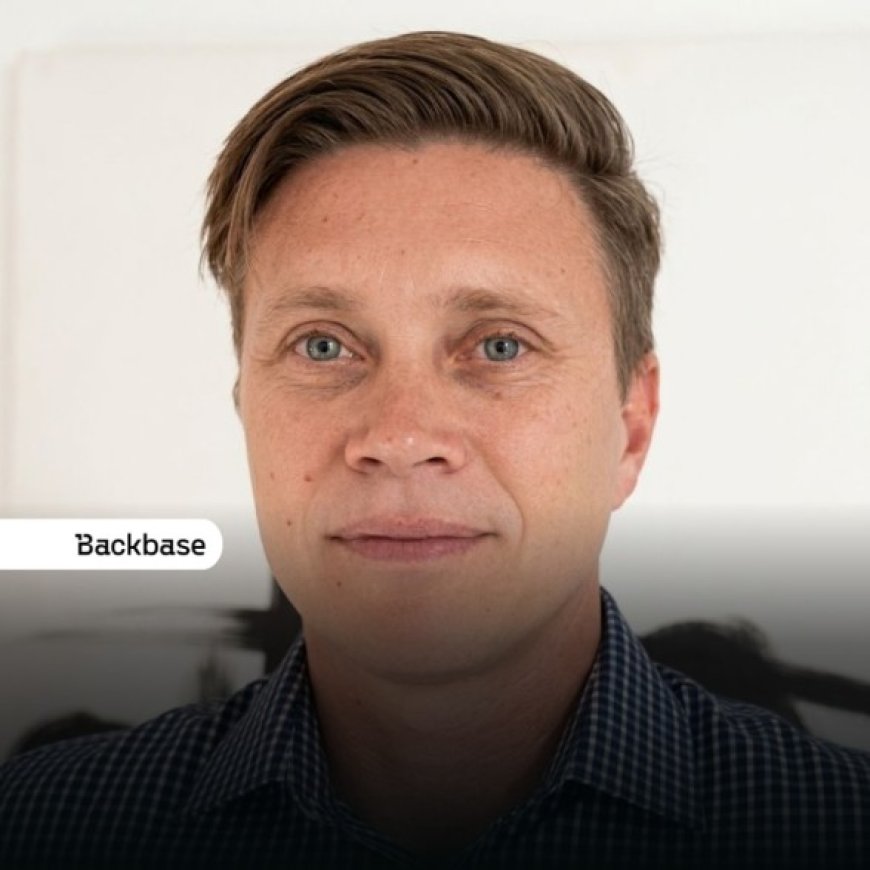
Article by: Justin Arnoldi, Managing Director EMEA and APAC, Backbase
There is a contradiction here worth examining. Banks have spent years optimising conversational technology around containment, deflection and cost-to-serve. These are important measures of operational efficiency, but they tell us surprisingly little about the quality of the customer relationship. Conversational AI can successfully prevent a customer from reaching an employee and still leave them frustrated. And therein lies the rub. Closing the ticket and strengthening the relationship are not the same thing.
A decade ago, the inability of AI to meaningfully bolster customer relationships was understandable. Rigid decision trees and predefined intents meant that when customers moved outside the script, the illusion of conversation and personalised service quickly collapsed. Today however, quantum leaps in natural language processing mean models can interpret ambiguity, maintain context and service far more complex requests. Making an AI agent sound more human is therefore no longer a breakthrough.
Industry gurus have romanticised personalisation for years, but personalisation on its own can be little more than a cosmetic improvement. Knowing a customer's name, preferred language, product holdings, or propensity to buy a credit card, may make an interaction more relevant. It does not necessarily make it more useful.
What really matters is context, and that goes much deeper. If a customer asks why a payment has not arrived, useful AI needs to understand which payment they mean, its current status, what happened when they contacted the bank yesterday and what options are available to resolve it. If the issue needs to move to an employee, that context should move with it. Asking the customer to explain everything again simply transfers the friction from one channel to another.
This is why the next phase of conversational banking is less a model challenge than an orchestration challenge. The intelligence customers encounter at the front end needs live access to customer data, transaction information, banking workflows and the appropriate controls governing what it can do. Without this, a sophisticated model sitting on fragmented systems risks only exposing that fragmentation.
The same principle applies when AI begins taking action. Knowing what the customer wants is only the first step. The system also needs to know whether an action is permitted, which workflow should execute it, what approvals are required and when the interaction needs human judgement. These foundations are what turn conversational AI from an impressive interface into something capable of actually banking. That’s the distinction. Customers don’t necessarily hate banking bots. But they almost certainly will hate bots that can’t bank.
Where the GCC tests this hardest
The GCC brings the challenges of context and orchestration into sharper focus. Customers across the region often switch seamlessly between Arabic dialects and English within a single interaction. They also tend to have multiple relationships with each financial institution, spanning salary and savings accounts, credit cards, loans, wealth management and more. When issues arise, the cause is often not the model itself, but the underlying data, workflows, language coverage, hand-offs and controls that support the conversation.
The regional context also sharpens the build-versus-buy decision. Hyperscalers have made it easier to build support agents, but they do not eliminate the need for robust governance and data orchestration. Banks must still determine whether the system can access the right context, adhere to policy, complete the required workflow and explain its actions. That is the build-versus-buy question that really matters.
Workforce planning adds another layer of complexity. Automation targets and national hiring commitments, including Emiratisation and Saudisation, often sit with different teams. Yet their effects converge on the same operating model and P&L. The question is not simply how quickly a bank can reduce service costs. It is which tasks AI should handle, which should remain the responsibility of employees, and where human judgement matters most.
For these reasons, AI initiatives rarely fail during the pilot stage. They fail in production, when the complexities of regional nuance, institutional context and operational delivery begin to compound.
From answering questions to anticipating needs
These considerations warrant a new way to think about conversational AI maturity. The progression is not simply from a basic chatbot to an increasingly intelligent chatbot. It is from answering, to advising, to acting and ultimately to anticipating.
Answering is where much of banking automation began. A customer asks a question and receives information. Advising introduces richer context, allowing AI to interpret the customer's circumstances and suggest an appropriate next step. Acting takes the next leap, connecting that intelligence to banking workflows so that, within clearly governed boundaries, the system can execute what the customer needs.
Anticipating is where the relationship changes most significantly. Instead of waiting for a customer to discover that an upcoming payment will leave their account short, the bank can recognise the issue beforehand. Rather than simply explaining the situation, it could identify available funds elsewhere and ask whether the customer wants to move them.
Each step requires greater context, orchestration and trust. Banks therefore should not rush towards maximum autonomy. The opportunity is to progressively expand what AI can do as the underlying data, workflows and governance mature alongside it.
From customer service to customer relationship
Market leaders are already heading in this direction, and Boubyan Bank offers a tangible example. Its digital assistant, Musaed, has evolved from a chatbot into a voice-enabled service that customers can access through the banking app or contact centre. Customers can ask questions in formal Arabic or Kuwaiti dialect and receive spoken guidance on accounts, cards and financing. That local language capability makes the experience distinctive as customers can approach the bank in the language they use every day, with less need to adapt to a scripted interface. It is a practical step towards making digital banking feel more accessible and familiar.
The opportunity for Middle East Banks is now to connect such ease of interaction with the context and ability to act that customers need. Success should be measured by problems resolved, effort reduced and trust earned. Closing a ticket may save the bank money. Giving customers confidence that their bank understands them and can help, is what earns their loyalty.
-Ends-
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0