MCB Bank Reports Resilient Performance with Strong Capital and Dividend Payout
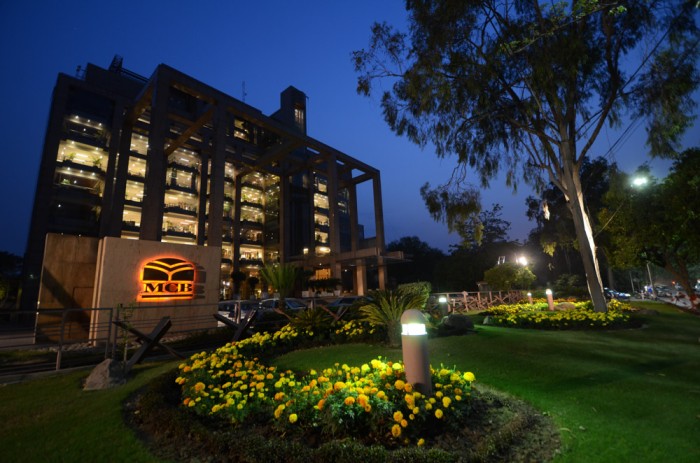
[Lahore: February 04, 2026] MCB Bank Limited is pleased to announce another year of resilient financial performance for the year ended December 31, 2025, reflecting the Bank’s strategic agility, balance sheet strength, and disciplined execution amid a dynamic macroeconomic and operating environment.
The Board of Directors of MCB Bank, under the Chairmanship of Mian Mohammad Mansha, reviewed and approved the Bank’s financial statements for the year ended December 31, 2025. The Board declared a final cash dividend of Rs. 9.0 per share (90%), bringing the total cash dividend for the year to 360%, including 270% already paid, reporting one of the highest dividend payout ratios in the industry.
For the year ended December 31, 2025, the Bank recorded a profit before tax (PBT) of Rs. 115.5 billion and a profit after tax (PAT) of Rs. 54.2 billion, translating into earnings per share (EPS) of Rs. 45.73. On a consolidated basis, PBT stood at Rs. 125.1 billion. These results underscore MCB’s prudent balance sheet management, sustained focus on core banking services and continued adherence to robust risk governance.
The interest rate easing cycle that commenced in June 2024 extended through 2025, resulting in a 2% year-on-year decline in net interest income. While the Bank delivered healthy growth in earning assets, the impact of higher volumes was largely offset by yield compression in the declining interest rate environment. This was partially mitigated by the Bank’s strategic emphasis on strengthening its no-cost deposit base, with current deposits increasing by 29% on an absolute basis and 22% on an average basis, reinforcing earnings sustainability and positioning the Bank favorably for future margin normalization.
Non-markup income amounted to Rs. 35.8 billion, reflecting a 4% year-on-year decline. Fee and commission income decreased by 9% to Rs. 19.3 billion, primarily due to heightened competition in the home remittance segment. Foreign exchange income increased by 11% to Rs. 10.2 billion, while dividend income registered strong growth of 45% to Rs. 5.1 billion.
The Bank continued to benefit from strong traction across its digital banking ecosystem, supported by growing customer adoption of digital channels. Card-related income increased by 18% year-on-year, driven by higher transaction volumes and enhanced product offerings. Branch banking fee income rose by 13%, supported by stronger customer engagement and cross-selling initiatives, while consumer banking fee income grew by 16%, reflecting increased customer activity and higher uptake of consumer financing products following the reduction in the SBP policy rate.
Operating expenses increased by 12% year-on-year, primarily reflecting continued investments in technology, talent development, and brand-building initiatives to support long-term growth. Despite the planned expansion in the cost base, the Bank maintained a healthy cost-to-income ratio of 37.73%, demonstrating strong cost discipline alongside its focus on operational efficiency and innovation.
On the balance sheet, total assets grew by 20% to Rs. 3.25 trillion, driven mainly by a 67% increase in net investments. Asset quality remained sound, with non-performing loans (NPLs) of Rs. 49.8 billion with coverage ratio of 92.47% and infection ratio of 6.76% which increased slightly due to reduction in gross advances YoY.
Deposits closed at Rs. 2.26 trillion, underpinned by a historic increase of Rs. 274 billion in current deposits, reaffirming the Bank’s strength in cost-effective deposit mobilization. This favorable shift in the deposit mix, coupled with the decline in the policy rate, resulted in a significant reduction in the domestic cost of deposits to 4.88%, compared to 9.98% in the corresponding year. The Bank reported Return on Assets (RoA) of 1.82% and Return on Equity (RoE) of 23.02%, while Book Value per Share improved to Rs. 205.59.
MCB Bank maintained its position as one of the leading players in the home remittance market, with a market share of 11%, processing USD 4,398 million in remittance inflows during the year. Leveraging its extensive branch footprint and expanding digital channels, the Bank continued to support the State Bank of Pakistan’s financial inclusion and formal remittance initiatives, contributing meaningfully to foreign exchange inflows and overall economic stability.
The Bank’s capital and liquidity positions remained robust, with the Capital Adequacy Ratio (CAR) standing at 19.53% and the Common Equity Tier-1 (CET1) ratio at 14.38%, well above the minimum regulatory requirements. Liquidity buffers remained strong, reflected in a Liquidity Coverage Ratio (LCR) of 267.35% and a Net Stable Funding Ratio (NSFR) of 163.71%. MCB’s credit ratings were reaffirmed by the Pakistan Credit Rating Agency (PACRA) at ‘AAA’ for long-term and ‘A1+’ for short-term through its notification dated June 23, 2025.
MCB Bank operates the second-largest branch network in Pakistan on a consolidated basis, with over 1,700 branches and continues to rank among the most capitalized and actively traded stocks on the Pakistan Stock Exchange.
Looking ahead, MCB Bank remains well-positioned to deliver sustainable growth, supported by its strong capital base, ample liquidity, diversified revenue streams, and disciplined risk management framework. The Bank remains focused on operational excellence, customer-centric innovation, and long-term value creation for all stakeholders.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0