
What LSE 24 Could Mean for Europe’s FinTech Infrastructure
What LSE 24 Could Mean for Europe’s FinTech Infrastructure
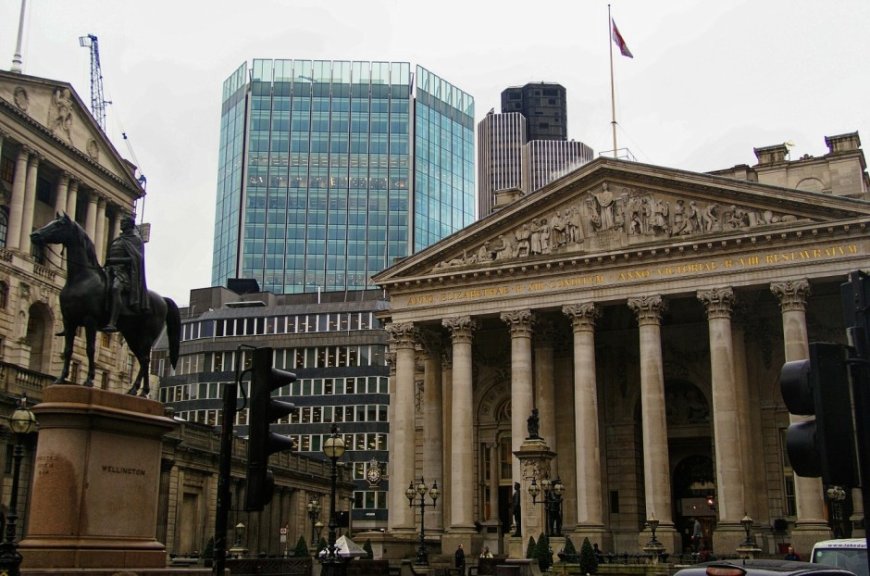
The London Stock Exchange Group (LSEG) has announced LSE 24: a dedicated overnight trading venue set to launch early 2027. Client testing begins at the end of 2026.
Historically, the exchange has restricted trading to standard daytime hours and closed entirely on weekends. LSE 24 breaks this pattern, however, operating as a separate platform with its dedicated order book, and with the overnight trading venue running from 5:00 PM to 7:50 AM London time every weekday – injecting an extra 14 hours and 50 minutes of trading capacity into the market.
The session will include a 30-minute pause between 6:30 PM and 7:00 PM. With this rollout, LSEG aims to accommodate the rapid rise in agentic trading while offering global investors more fluid access to European capital markets.
Initially, LSE 24 will be restricted to Exchange-Traded Products (ETPs), or funds that track indices, commodities, or other assets and trade like stocks, rather than individual equities.
Julia Hoggett, CEO of London Stock Exchange PLC, noted that the venue will “provide clients with greater flexibility beyond traditional trading hours” as well as support “more digital, connected global markets.”
LSEG is not acting in a vacuum; it is responding to shifts in global market demands. Retail expectations have evolved largely due to cryptocurrency exchanges operating around the clock, prompting traditional exchanges to reconsider their trading hours. Advanced algorithmic and agentic systems also require continuous connectivity to manage portfolios efficiently and international clients, particularly in Asia, want to trade during their local daytime hours, rather than waiting for European bells to ring.
Major venues across the European and U.S. markets have already moved in this direction. Germany’s Eurex derivatives exchange is one such example, maintaining a 21-hour continuous trading cycle across global time zones so international clients can trade during their local hours. The New York Stock Exchange and NASDAQ have received regulatory approval to extend trading to 22-hour and 23-hour weekday sessions, respectively. LSE 24 positions London beside them, rather than behind them.
But extending trading hours at the exchange itself is only part of the equation. The venue’s availability does not automatically translate into access for investors. Andrey Dobrynin, CEO of ETF broker InvestEngine, told Fintech News Media that “access will depend on whether individual investment platforms choose to offer trading through LSE 24.”
For fintechs, that choice raises a fundamental question: what has to change in the infrastructure to make 24/5 trading viable?
LSE 24 disrupts the overnight maintenance windows that investment platforms and prime brokerages typically use for system updates, database optimisation, and batch risk calculations. Operating during the full trading cycle — from Main Market into the overnight session — means brokers need to maintain uninterrupted order routing, live market-data feeds and institutional Order Management Systems.
Moving beyond rigid maintenance windows to an always-on architecture is often resource-intensive, favouring larger platforms over smaller brokerages. But it protects investors from overnight market shocks, especially when backend systems can process stop-loss orders, trigger liquidations, or automate margin adjustments in real time.
T+2 cycles to continuous clearing
While North American counterparts have moved to T+1, European post-trade infrastructure remains reliant on T+2 settlement cycles and overnight batch processing. LSE 24 complicates that model by introducing a trading venue in the overnight window reserved for reconciliation and other post-trade processes.
With LSE 24 launching in early 2027, months before Europe’s planned shift to T+1, fintech infrastructure providers will have to adapt to both a shorter settlement cycle and less downtime for post-trade processing.
Consequently, clearing houses like LCH and payment rails like EBA Clearing's RT1 must shift to continuous transaction matching. Fintech infrastructure providers, including connectivity APIs and digital custody networks must also synchronise trade data continuously across venues to reduce the risk of overnight settlement failures.
RegTech and surveillance
Under the FCA Market Abuse Regulation (MAR), trading firms are legally required to maintain automated surveillance software capable of spotting manipulative patterns. In thinner overnight markets, unusual price movements or sudden order-book updates become increasingly difficult to distinguish from legitimate trading, causing rigid surveillance software to generate a wave of false positives.
Simply put, regulatory technology systems cannot rely solely on daytime metrics. They must be recalibrated using dynamic parameters like volatility multipliers and materiality filters to account for the unique liquidity conditions of overnight trading.
With the arrival of LSE 24, fintech providers are being forced to overhaul their legacy systems at a time when regulatory demands are already peaking, from plans to transition to T+1 settlement to the compliance hurdles of the FCA.
When you stack retail platform instability on top of clearing friction and algorithmic noise, the true cost of an “always-on” stock exchange becomes clear. One point of failure can snowball quickly: an unstable retail platform could prevent investors from reacting to overnight market shocks before portfolios take a hit; a clearing delay could leave trades unresolved across time zones; a surveillance system flooded with false positives could trigger regulatory scrutiny at the worst possible moment.
What appears to be a simple commercial expansion, is in reality, an aggressive stress test of Europe’s financial technology. If these underlying systems cannot handle the pressure, longer trading hours will simply mean a longer window for operational errors and inflated trading costs. This explains Dobrynin’s argument that LSE 24’s success “should be judged on the quality and cost of execution it provides, rather than the number of hours during which trading is available.”
For Gulf and Asian investors, the timing finally works
For most European retail investors, the overnight window is unlikely to change much — at least in the short term. Retail traders do not interact with the LSE directly; they access markets through brokers. Most European retail brokers are unlikely to update their technology to support overnight trading immediately, given the significant costs involved.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0